Who can apply
Resident or part-year resident eligibility follows federal EITC rules, with a state exception for otherwise eligible people lacking qualifying taxpayer identification numbers. Residency affects the calculation.
What help is available
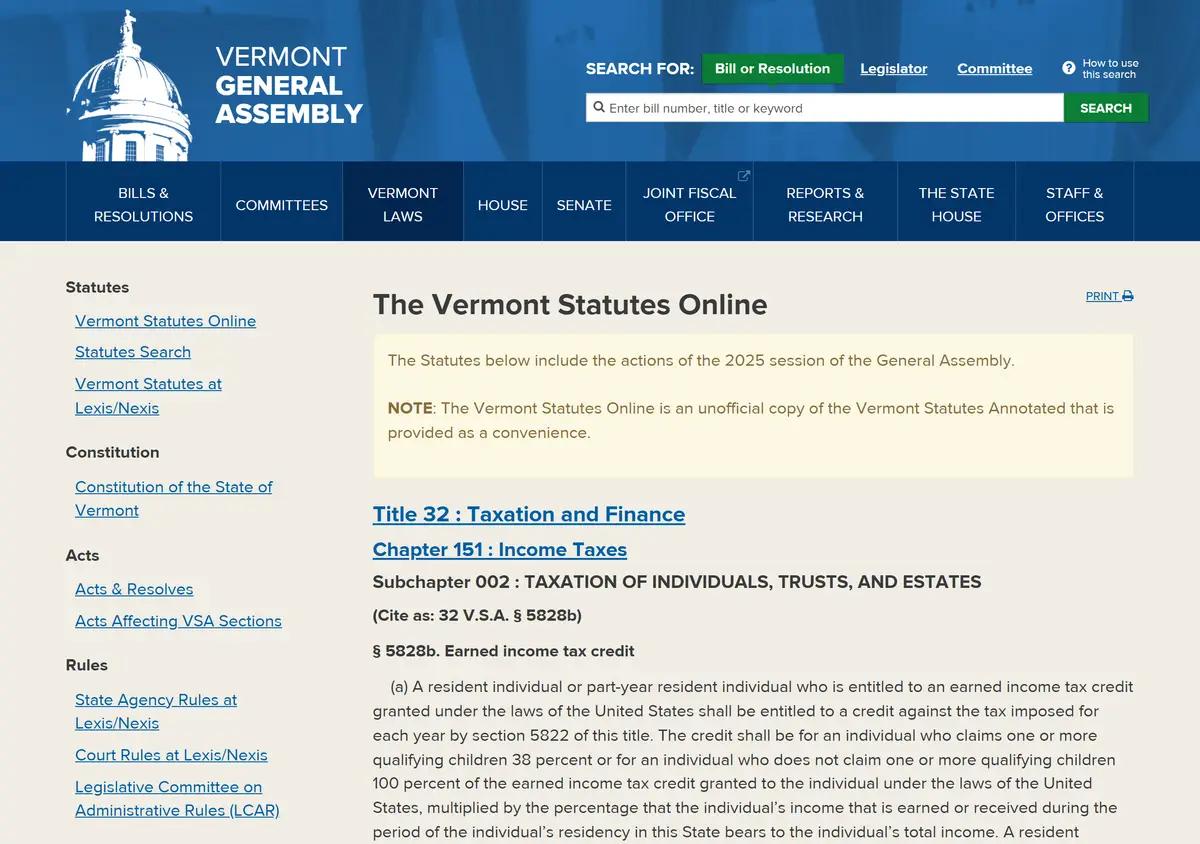
Current statute provides 38% of federal EITC with qualifying children or 100% without qualifying children, adjusted for the residency-income ratio. Check the filing year’s instructions.
Documents to prepare
- Federal EITC calculation.
- Wage and qualifying family records.
- Vermont return and residency information.
How to get started
Select the filing year
Use the matching Vermont forms and instructions.
Complete the credit calculation
Apply the relevant child and residency rules, including any identification-number exception.
File and retain evidence
Keep the federal calculation and state return.
After applying
The current statutory percentage should not be substituted into a prior-year return without checking that year’s instructions.
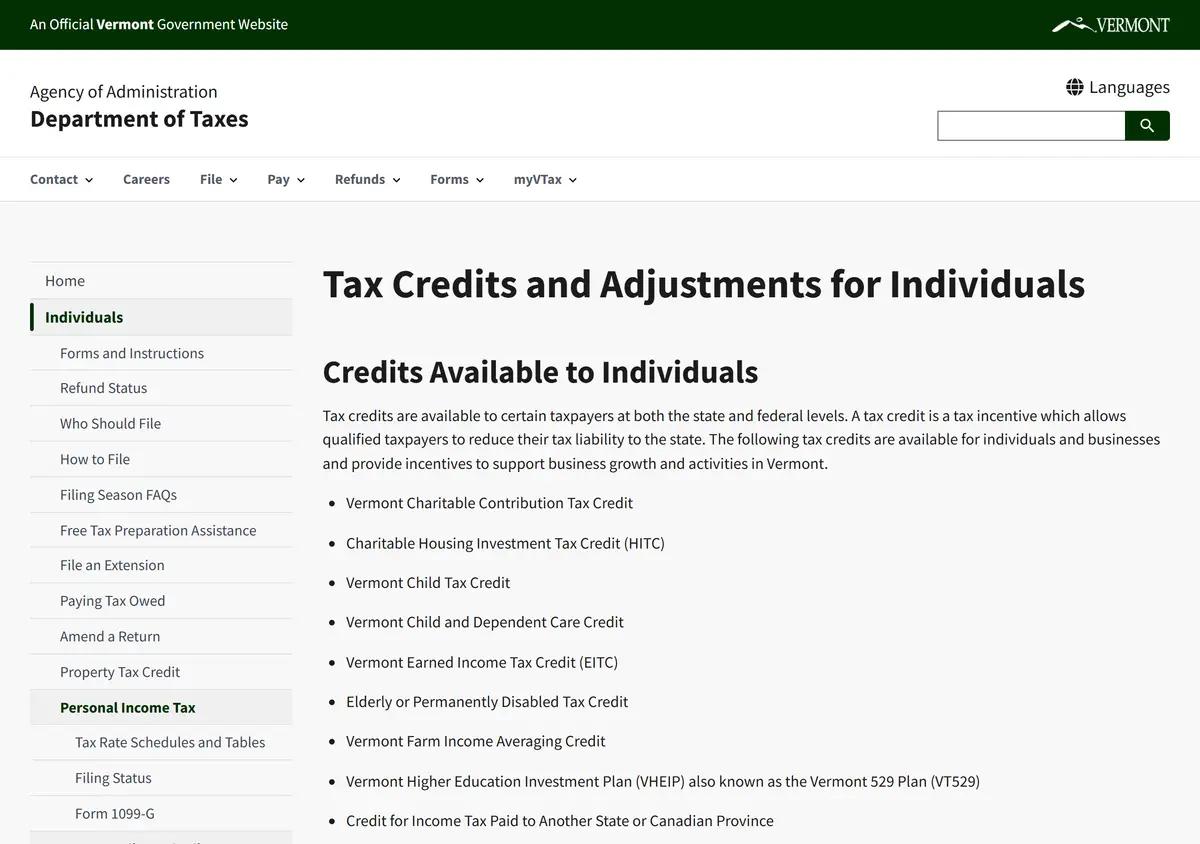
Website screenshots
These images show the pages captured in August 2026. Website screens and rules may have changed.
Common questions
Is one percentage used for everyone?
Current law distinguishes qualifying-child and no-child cases.
Can the credit exceed tax owed?
Yes. The statute provides payment of the excess.
Does part-year residence matter?
Yes. The residency-income ratio affects the credit.
Is this a myBenefits application?
No. Claim it through income-tax filing.
Sources and review
Content checked October 1, 2026 using Current Vermont EITC statute. Current eligibility and the final decision remain with the program.
Historical screenshots: source reference.